A suggestion is a session waiting to start.
Michael and Laura Prescott’s plan settled on two health savings accounts for 2026, funded from their savings. Months later, no HSA was on record. Nobody had dropped the ball on purpose; it was simply the kind of step that waits for someone to pick it up. Helmsted noticed the gap and put it on their advisor’s Home screen, under Suggested next:
“Open Michael and Laura’s HSAs and move $10,750.”
The reason it gave was the part that matters to the clients: medical bills from before the accounts open can never be reimbursed, so each month they wait costs them.
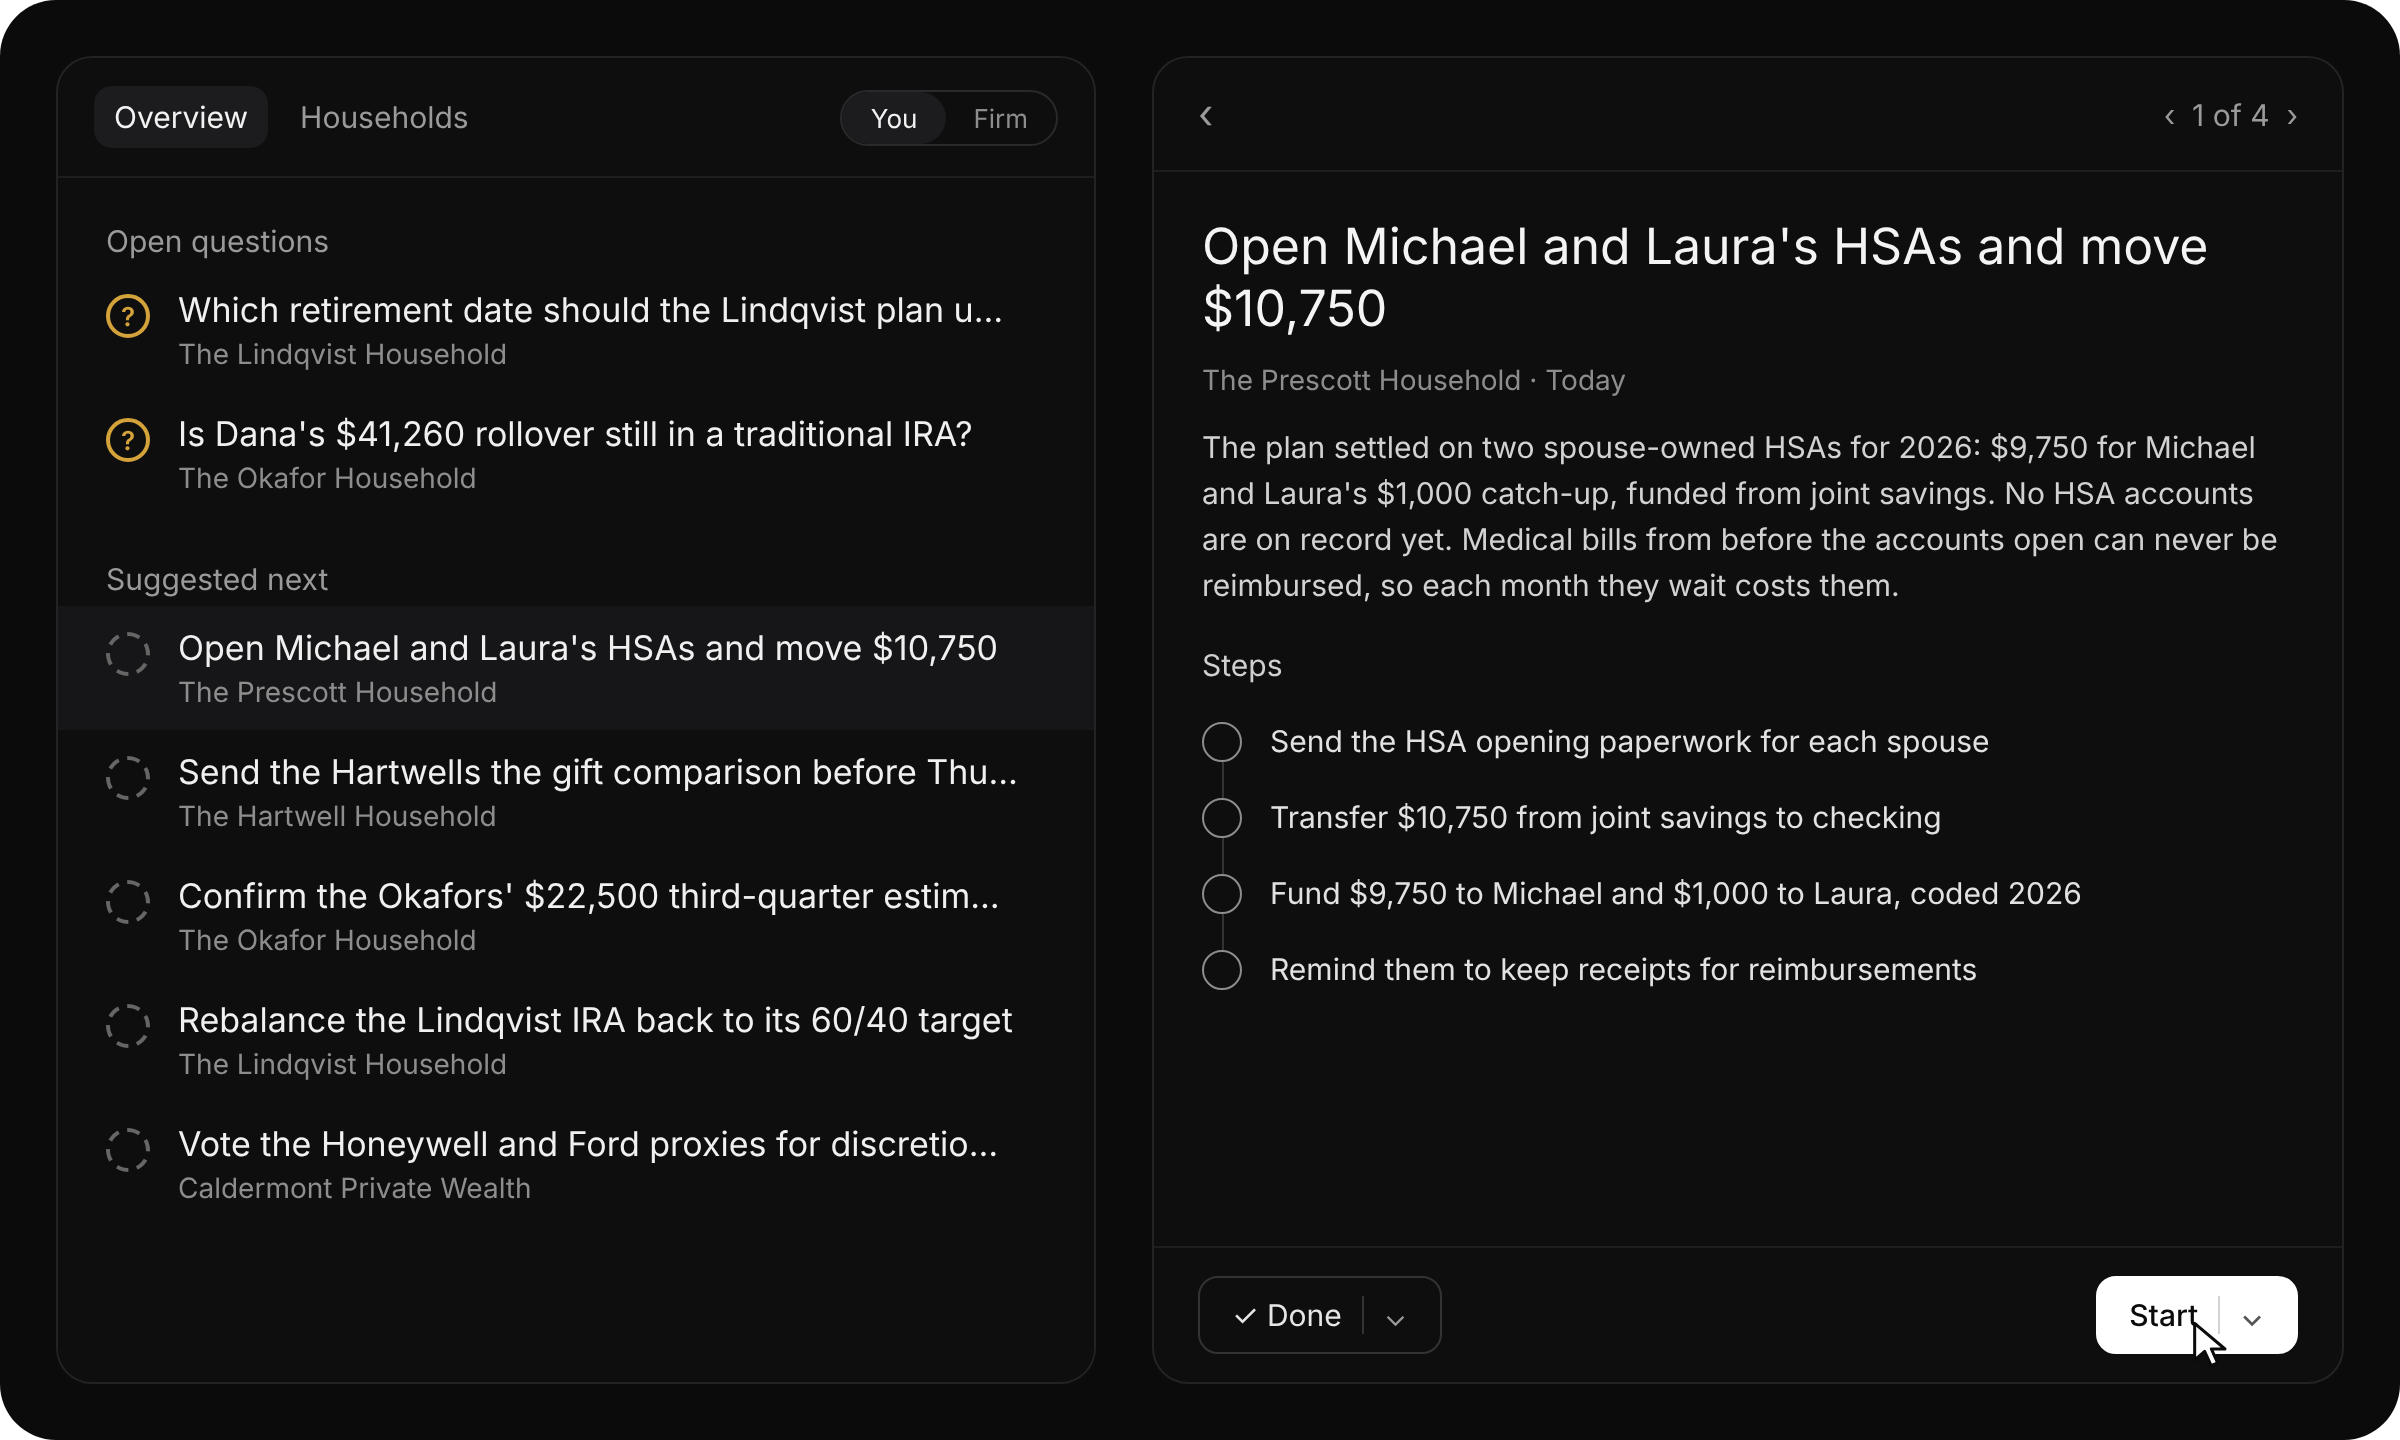
1. Start. One click on the suggestion opened a session, and Helmsted gathered the context itself: the plan that called for the HSAs, Laura’s benefits enrollment, both birth years and the savings balance. No re-explaining the household.
2. “Check they’re both eligible and show me the split.” Helmsted confirmed the family plan qualifies (a $4,000 deductible against the $3,400 minimum), that neither spouse is on Medicare and that Laura’s employer makes no HSA contributions. Then the split: the family limit is $8,750 and both are over 55, but each $1,000 catch-up has to go into that spouse’s own account. So $9,750 to Michael and $1,000 to Laura.
3. “Where should the money come from, and what’s the deadline?” Their joint savings, which sits above the six-month reserve the plan calls for. 2026 contributions can wait until April 15, 2027, but the accounts should open now: only expenses after an HSA is established can be reimbursed from it.
4. “Write it up for Michael and Laura with what each of them needs to do.” A one-page plan in the firm’s brand: the split, the funding, the roughly $2,580 of federal tax the contributions save at their 24 percent bracket, and a checklist with who does what and by when. It can go straight to their portal.
Then one more line: “Draft the emails.” Helmsted wrote two: one to Michael and Laura with the plan and the forms each of them signs, and one to the HSA provider asking for the account-opening packets. The advisor reviews and sends. And the suggestion takes care of itself: once Helmsted sees both accounts open and funded, it clears from the list.
It learns with the firm
Every suggestion an advisor starts, finishes or clears tells Helmsted something about how the firm works: which steps matter, who usually handles them, and what a good client plan looks like at this firm. Over time the suggestions get sharper and the sessions start closer to done.
Where this is going
Today the session gathers the context, builds the plan and drafts the emails, and the clicking in between, the HSA provider’s site and the bank transfer, is still done by the advisor or the client. Helmsted will keep evolving to handle more of that work itself, always with the advisor’s approval before anything that signs, sends or moves money. This part of Helmsted is going to change quickly over the coming weeks, and we will keep pushing how much of each step it can carry. Suggested next becomes the start of the work, not a reminder of it.
Advisors decide. Helmsted executes.
Getting creative with materials with Helmsted
Ask for the version each person needs. The same session produced the client’s one-page plan, the advisor’s checklist and the two emails, each written for who reads it. Keep the why next to the what. The plan explains the reimbursement rule in one sentence, so the urgency reads as advice, not nagging.
One thing makes all of it work: context. Helmsted needs the benefits enrollment (plan type, deductible and start date), any employer HSA contributions, both spouses’ birth years and Medicare status, and the account it should fund from.